Planning on selling your Maine or Florida condo?
Know your grade before you sell.
Since August 3, 2026, most conventional condo loans sold to Fannie Mae or Freddie Mac require a Full Review of your association. Projects with 10 or fewer units may qualify for a waiver. For loan applications dated on or after January 4, 2027, the association's budget must also put at least 15% of its assessment income into reserves, up from 10%. If your association falls short, buyers who need a conventional loan may not be able to finance your unit.
Based on Fannie Mae and Freddie Mac conventional loan guidelines. FHA and VA have separate condo approval processes.
If you plan to sell in the next 12 to 24 months, know where your building stands before you list, not after a buyer's lender reviews it.
Free · About 3 minutes · Know your grade and how it could affect your saleability.
Enter your name and email at the end to see your results.
- Reserves & budget
- Master insurance & deductibles
- Critical repairs
- Dues delinquencies
- Single-entity ownership
- Pending litigation
- Special assessments
Most buyers finance: in NAR's 2025 Profile of Home Buyers and Sellers, 26% of buyers paid all cash. When conventional financing isn't available for a building, the buyer pool can narrow, and Cotality found that in 2025 all-cash purchases closed at an average 9% discount to financed ones (all property types).
Full Review is now standard
Lenders selling conventional loans to Fannie Mae or Freddie Mac can no longer use the quicker Limited (Fannie Mae) or Streamlined (Freddie Mac) review for established projects. A Full Review looks at the association's reserves, insurance, delinquencies, litigation and critical repairs. Projects with 10 or fewer units may qualify for a waiver.
Reserves rise to 15%
The association's budget must allocate at least 15% of annual assessment income to replacement reserves, up from 10%. A lender may instead rely on an acceptable reserve study, but only if the budget funds the study's highest recommended level. This is a lender guideline, not Maine law.
Insurance and repairs
Master policies must cover 100% of replacement cost. Deductibles are capped at 5% of the policy amount per occurrence and $50,000 per unit. Critical repairs, including unfunded repairs over $10,000 per unit due within 12 months, can make a project ineligible.
Investor cap retired
For established projects, Fannie Mae retired its 50% investor-concentration limit and Freddie Mac its 50% owner-occupancy requirement. Single-entity limits still apply.
Now the building has to qualify, not just the buyer.
Even a buyer with excellent credit and a large down payment may not be able to get a conventional loan on a condo whose association falls short. Knowing where your building stands is the first step.
CR-2026-00417
Assessed 06 / 2026
Narrowing
- 01Project size · 24 unitsPass
- 02Reserve study · currentPass
- 03Reserve funding · 11 percentFlag
- 04Critical repairs · roof unfundedFail
- 05Master insurance · replacementPass
- 06Delinquencies · 9 percentPass
- 07Single entity · 8 percentPass
- 08Special assessment · plannedFlag
The Condo Ready Score is an educational self-check based on your answers and Fannie Mae and Freddie Mac conventional guidelines. It is not a lender's project approval or a guarantee of financing; each lender makes its own eligibility decision. FHA and VA have separate condo approval processes.
Answer 8 questions, then enter your name and email to see your own report. Your results are shared with Deja Lett, who can walk you through what they mean.
The Condo Ready Score
Have these handy for the most accurate score: your HOA's reserve study, current budget, and master insurance policy. Don't have them? Estimate, we'll confirm on your free review.
8 quick questions · about 3 minutes
Deja Lett, Broker
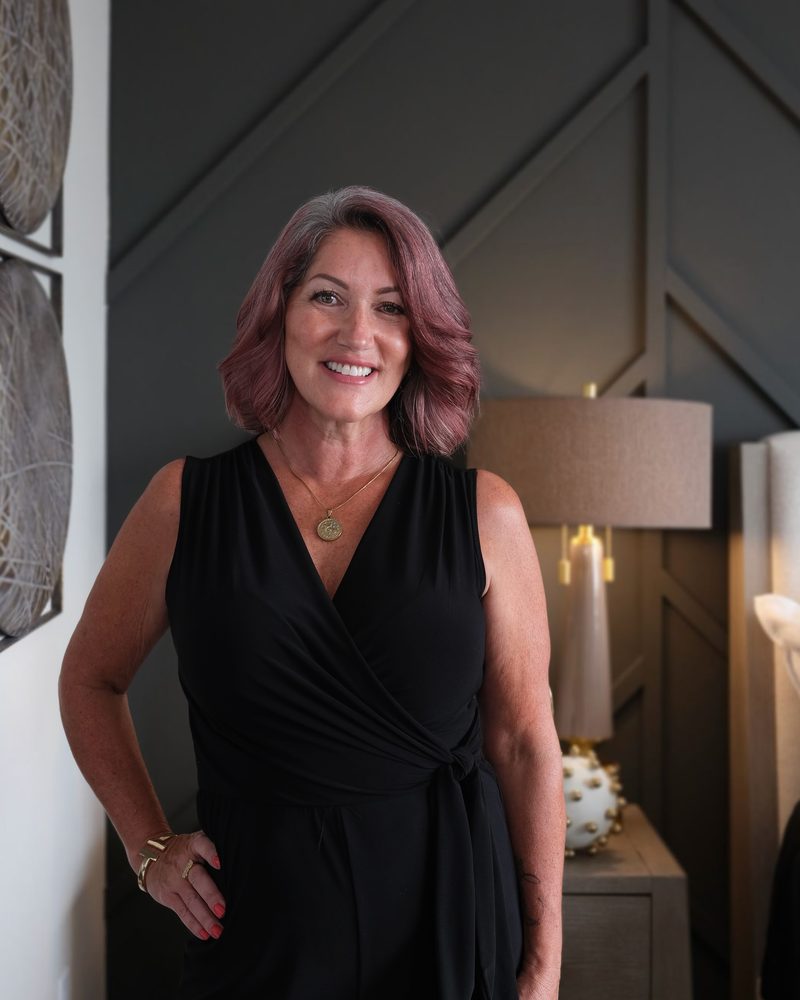
Broker and founder of Top Homes Group at Keller Williams Realty, serving Southern Maine and Tampa Bay. Licensed in Maine and Florida: ME BR916256 · FL SL3530339. She positions your condo and runs the sale.
tophomesgroup.com →One expert. Both sides of the move. You are never handed to a stranger.
Top Homes Group | Keller Williams Realty
What condo owners ask us most
Book your free review with Deja
No pressure, no obligation. We'll review your Condo Ready Score together and map out your best options before you list.